Paying for veneers: financing and insurance
Most people pay for veneers with a dental office payment plan, third party financing like CareCredit, or savings. Dental insurance rarely covers veneers because the work is cosmetic. Financing spreads the cost into monthly payments, sometimes with a promotional interest free window if you pay off the balance in time.
Key takeaways
- Cosmetic veneers are rarely covered by dental insurance because they are elective.
- In office payment plans and third party financing spread the cost into monthly payments.
- Promotional interest free windows exist, but interest applies if you miss the payoff date.
- HSA and FSA funds may cover veneers only when the work is medically needed, not cosmetic.
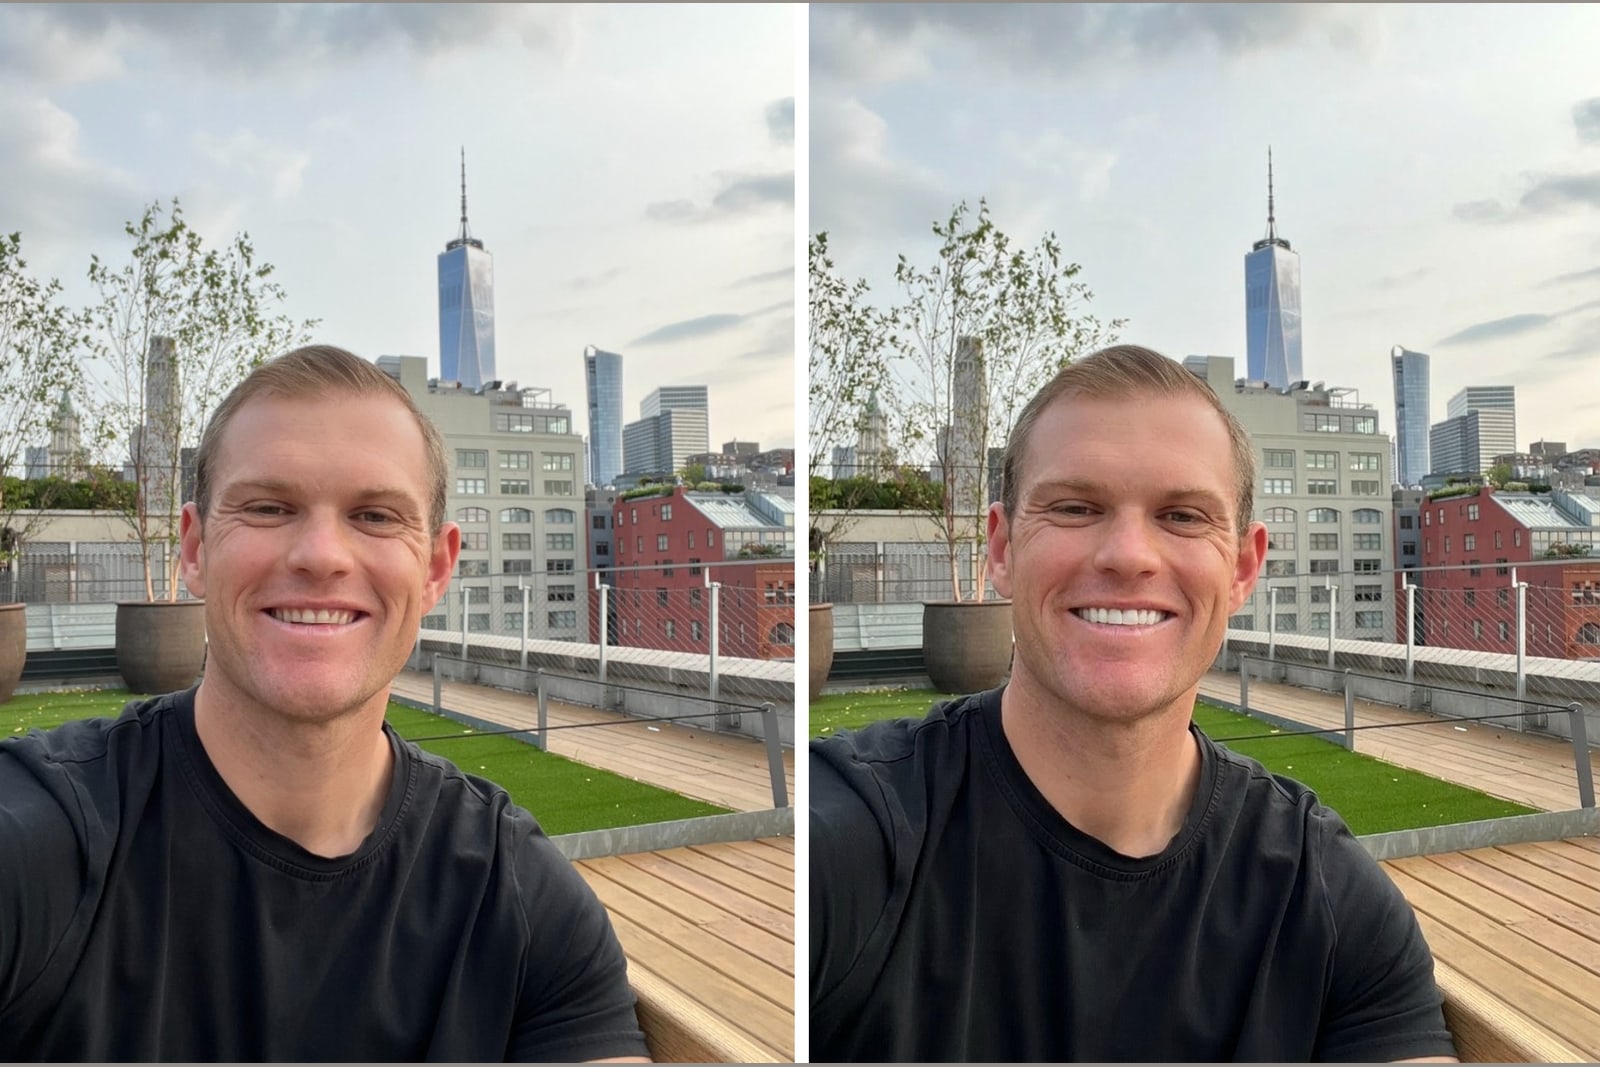
- Preview your look first so you fund a smile you already know you want.
Veneerly is an aesthetic preview tool. It is not dental or medical advice and it is not a substitute for a consultation with a licensed dentist.
Does dental insurance cover veneers?
Dental insurance rarely covers veneers because they are classed as cosmetic and elective. Insurance is built to pay for work that restores health and function, like fillings, crowns on damaged teeth, or root canals. Veneers change the appearance of teeth that are already functional, so they sit outside most plans.
There is one narrow exception. If a veneer or a crown is placed to restore a tooth that is cracked, worn, or damaged, part of that work may be considered restorative. In that case a portion could be covered. Always ask your dentist to submit a pre treatment estimate to your insurer so you know before the work begins.
How do people pay for veneers?
Most people pay for veneers with one of four methods: savings, an in office payment plan, third party dental financing, or a health account when the work qualifies. Since a full set of veneers is a real expense, understanding how much do veneers cost first helps you pick the right funding path.
| Payment method | How it works | Best for |
|---|---|---|
| Pay in full | One payment from savings, often with a small cash discount | People who want no interest and no application |
| In office payment plan | The dental office splits the cost across set months | People who want to avoid a third party lender |
| Third party financing | A lender like CareCredit or LendingClub funds the treatment | People who want a longer term or a promotional window |
| HSA or FSA | Pre tax health dollars, only if the work is medically needed | People whose veneers restore damaged teeth |
| Personal loan or credit card | A bank loan or card covers the balance | People comparing rates across lenders |
What are in office payment plans?
An in office payment plan is an arrangement directly with your dental office that splits the total cost into monthly payments. Some offices run these themselves without interest, and some partner with a financing company that handles the billing. Terms vary by office, so ask three questions up front: how many months, is there interest, and is a deposit required.
Because these plans are set by the office, there is room to discuss the schedule. Some offices reduce the total if you pay a larger deposit or complete payment within a shorter window.
How does third party dental financing work?
Third party financing means a lender pays the dental office for you, and you repay the lender in monthly installments. CareCredit, LendingClub Patient Solutions, and Sunbit are common names in dental offices. You apply, get approved for a limit, and choose a term.
Many of these lenders offer a promotional interest free window, for example six or twelve months. This is the key detail to understand:
- Deferred interest means no interest applies only if you pay the full balance before the promotional window ends. Miss the date and interest is charged back to the original purchase date.
- True zero percent means no interest for the promotional period regardless, but this is less common.
- Standard APR applies once any promotional window closes, and dental financing rates can be high, so read the terms.
Approval and rate depend on your credit. Compare the promotional length, the ongoing APR, and any fees before you sign.
Can I use an HSA or FSA for veneers?
You can use a health savings account or flexible spending account for veneers only when the work is medically necessary, not purely cosmetic. Restoring a broken or badly worn tooth may qualify. Whitening or changing the shape of healthy teeth does not. Because the rules are specific, ask your dentist for documentation and check with your account administrator before you assume the cost is eligible.
How to budget before you commit
The smartest step before any financing application is deciding whether the change is right for you and which look you actually want. Veneers are permanent, so funding a design you are unsure about is the wrong order of operations. Read our honest take on whether veneers are worth it to weigh the trade offs.
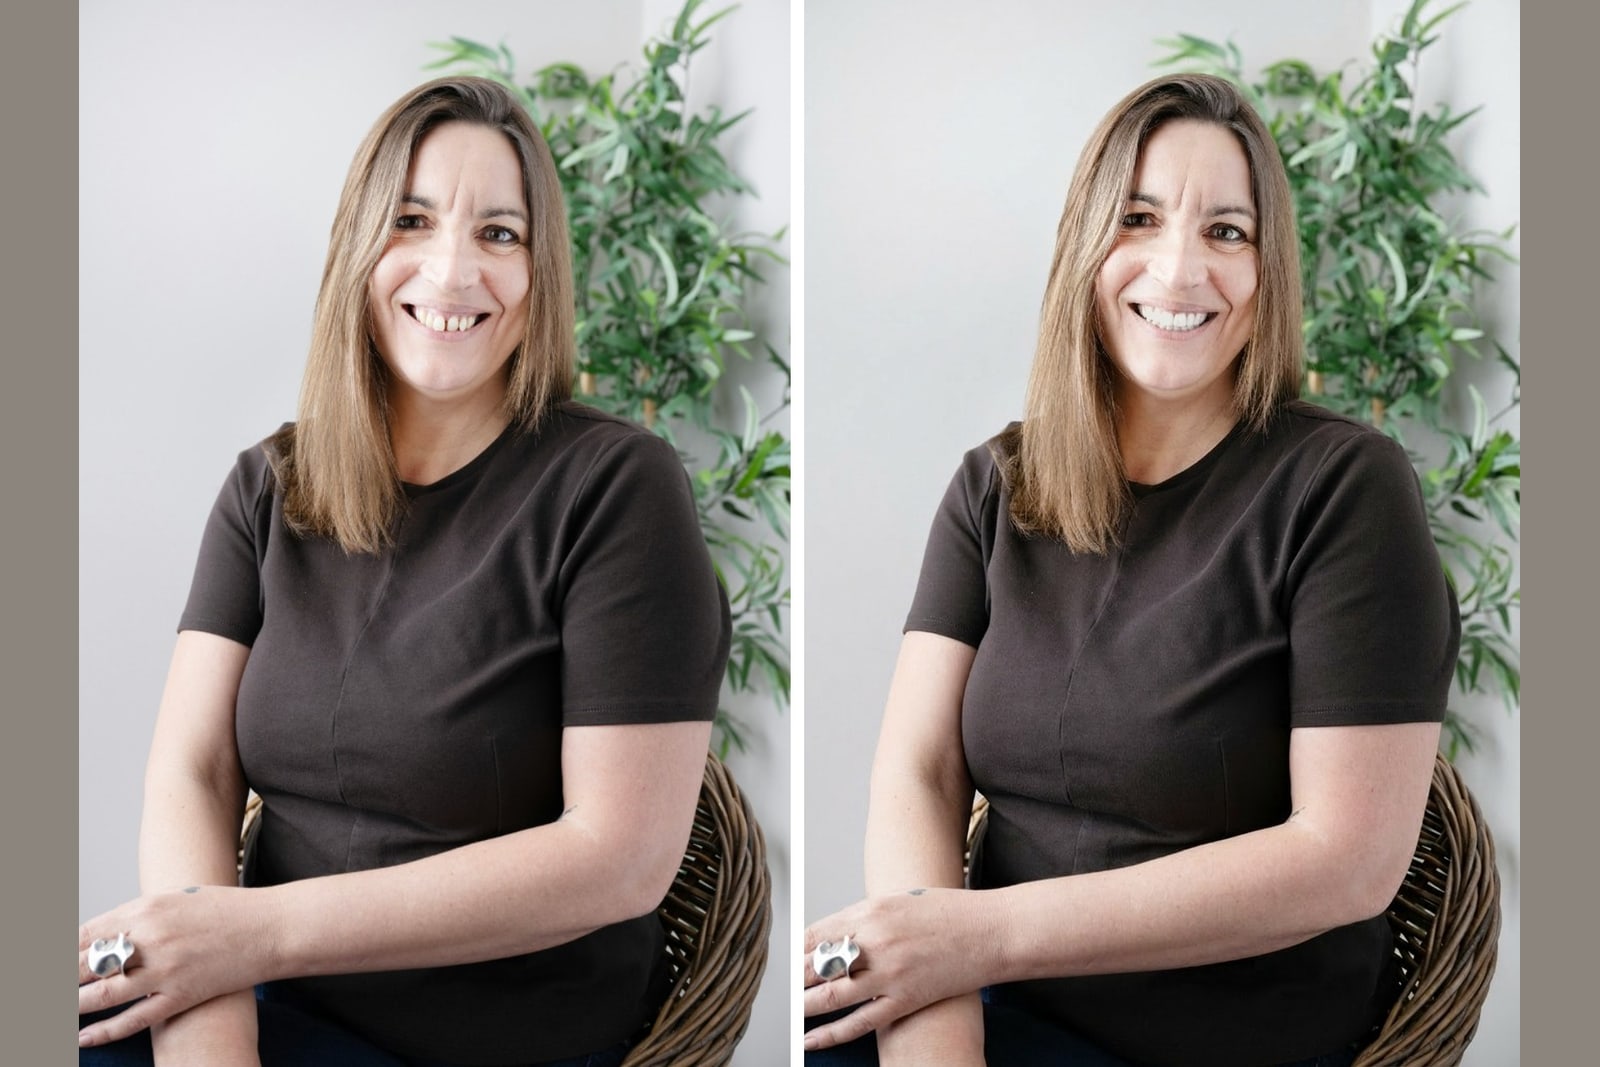
Veneerly lets you settle the look side first for a one time payment from 39 dollars. You upload your own photo and get ten designs across five styles in about 60 seconds, with six shades from Natural Ivory (A1) to Ultra White (BL1). Only the teeth change in the image. Knowing exactly which style and shade you want means the money conversation with a dental office is faster and more concrete.
Questions to ask before you finance
- What is the full cost of the treatment, including any temporaries and adjustments?
- Does the office offer an in office plan, and is it interest free?
- If I use third party financing, is the promotional period true zero percent or deferred interest?
- What is the ongoing APR after any promotional window, and are there application or late fees?
- Could any part of the work be submitted to insurance as restorative?
Frequently asked questions
Does insurance ever pay for veneers?
Dental insurance rarely pays for veneers because they are cosmetic. The exception is when a veneer or crown restores a cracked, worn, or damaged tooth, in which case part of the cost may be considered restorative. Ask your dentist to submit a pre treatment estimate to your insurer.
What credit score do I need for dental financing?
Requirements vary by lender, and approval and interest rate depend on your credit profile. Some lenders like Sunbit approve a wider range of scores, while promotional zero percent offers often favor stronger credit. Apply with the specific lender to see your terms before committing.
What does deferred interest mean on dental financing?
Deferred interest means you pay no interest only if you clear the full balance before the promotional window ends. If any balance remains after that date, interest is charged back to the original purchase date. Read the terms so you know the exact payoff deadline.
Can I use a payment plan and insurance together?
Yes. If part of your treatment qualifies as restorative, insurance may cover that portion, and you can finance the remaining cosmetic balance through an in office plan or a third party lender. Get the insurance estimate first so you know the amount you actually need to finance.
Is it cheaper to pay for veneers in full?
Often, yes. Paying in full avoids interest, and some offices offer a small cash discount. Financing spreads the cost but can add interest once any promotional window closes, so compare the total you would pay each way.
See your smile before you finance it
Upload one photo and get ten designs across five styles in about 60 seconds, from a one time payment of 39 dollars.
Preview my smile